

Ualett
by Cabicash Solutions, Inc
4.6
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.6
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
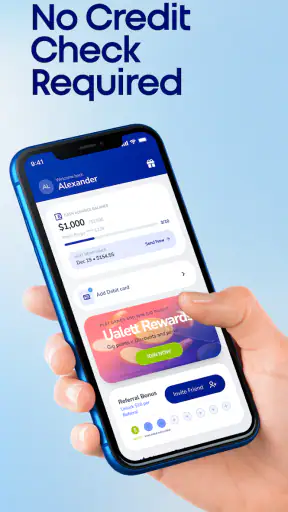
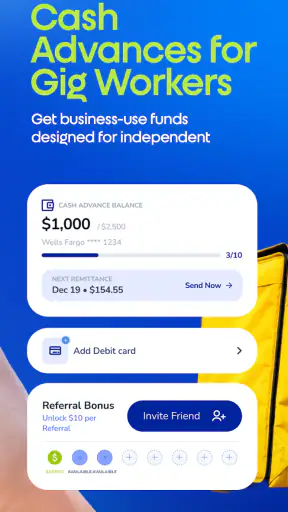
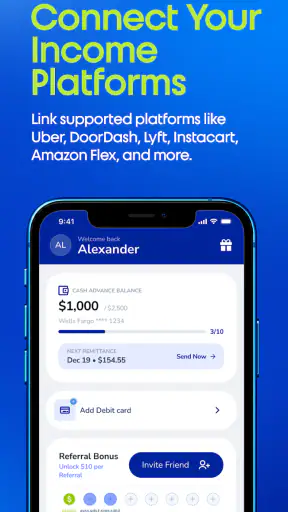
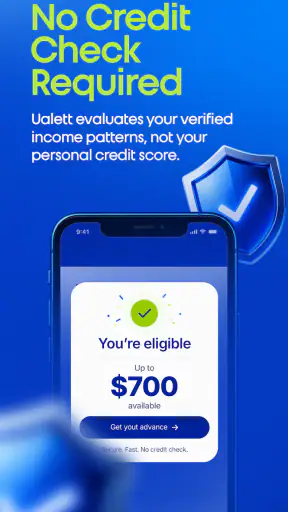
 Analysis by Getfullapps
For gig workers, money rarely arrives in a neat monthly rhythm. One week can be busy, the next can be slow, while fuel, phone bills, groceries, and other everyday costs continue on schedule. Ualett is a finance app built around that uneven working pattern, and I found its appeal much clearer when viewed as a tool for managing access to earnings rather than as a general replacement for a bank.
My first impression is that the app is aimed at a very specific person: someone who earns through gig work and wants a financial service shaped around that reality. That focus matters. A traditional banking app may be perfectly good for checking balances and moving money, but it does not necessarily feel designed for income that changes from day to day. Ualett’s identity is more practical and narrower, which can be a strength if your work fits the intended audience.
It is free to download, rated for Everyone, and maintained by Cabicash Solutions, Inc. The app has been available since Aug 21, 2018, and its current version is 2.73.0 with Android support from 8.0 onward. Its audience is not tiny either: it has passed 500K installs, with a 4.6 average from around 7.6K ratings and roughly 1.3K written reviews. Those figures suggest meaningful use, but I would still treat popularity as context rather than proof that it will suit every worker.
How Ualett Builds Trust for Gig Workers
I’d use this section to look at trust as a set of everyday choices, not just a reassuring rating: checking who publishes the app, reading consent prompts, and keeping a clear record of money-related activity. For a gig worker, that careful routine matters most when income is uneven and decisions feel urgent. It also leads naturally to the practical question of how to make the app fit into a repeatable weekly workflow.
A focused financial purpose
The strongest trust signal I see is the app’s clear positioning. Ualett does not present itself as an all-purpose money manager for everyone. Its store summary is “Built for Gig Workers,” and that gives a prospective user a useful starting point: the service is trying to solve a particular income problem, not simply add another generic finance dashboard to a phone.
That focus also creates an important expectation. Before relying on it, I would ask whether my own work arrangement matches the app’s intended workflow. A delivery driver, rideshare worker, or independent contractor may have a different experience from someone paid through a regular payroll system. If your income is already predictable and your employer pays on a fixed schedule, the specialized angle may offer little benefit compared with your existing bank.
I also like that the app’s age rating does not make it sound like a niche product restricted to a narrow demographic. Still, an Everyone rating is about suitability of content, not a promise that every financial situation is supported. I would separate those two questions before opening an account: “Can I use this app?” and “Does it solve the cash-flow issue I actually have?”
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
What the public signals can and cannot tell you
The rating history gives Ualett a reassuring first impression, especially because there are both many ratings and a substantial set of written reviews. Yet finance apps deserve a more careful reading than entertainment apps. A high average can reflect a smooth sign-up experience for one person while saying less about an unusual income pattern, a delayed payment, an account review, or the process of leaving the service.
When I assess an app like this, I look beyond the star number. I want to know what information is requested, which choices are visible before I commit, how clearly the app explains account actions, and whether I can understand the consequences of using a particular feature. Those are the areas where trust becomes practical. A polished interface is helpful, but it should not replace careful reading at moments involving money or personal information.
The developer name, Cabicash Solutions, Inc, is also worth noting when checking support material or account documentation. If I needed help, I would make sure I was contacting the official developer channel associated with the app rather than responding to an unrelated message. That simple habit is especially important for finance products, where impersonation attempts can look convincing.
Permissions and data-sensitive moments
Permissions are one of the first things I would inspect during installation. I would avoid granting access automatically and instead read each request in context. If a permission appears necessary for a specific action, I would consider it at that point; if it seems unrelated to what I am doing, I would pause and look for an explanation in the app’s privacy information or device settings.
I would apply the same caution to personal and financial details. Gig workers often need to share more information with financial services than they would with a simple budgeting tool, so I would enter data only through the official app and verify that the screen is secure before continuing. I would not send sensitive details through ordinary chat, social media, or an unsolicited support message, even if the sender uses the app’s name.
There is a useful distinction here between convenience and permission. A service may ask for information because it needs to identify an account or evaluate an action, but that does not mean I should stop reading. I would check the purpose of each request, review any consent screen rather than tapping through it, and revisit device permissions later if I no longer use a related function.
Account control matters as much as access
A financial app should be judged not only by how quickly it helps a user get started, but also by how clearly it lets that user remain in control. In Ualett, I would pay close attention to account settings, notifications, connected services, and any option that changes how money is accessed or communicated. I would keep alerts enabled for important activity while avoiding unnecessary notifications that make genuine account messages harder to notice.
I would also keep my login details unique and protect the phone itself with a strong screen lock. If the device is shared, lost, or replaced, I would review the account immediately from a trusted device and remove access where possible. These steps are not glamorous, but they are more valuable than relying on a five-star rating as a substitute for account security.
Another practical control is record keeping. I would save confirmations, note the date of important requests, and compare app activity with my own bank records. This is particularly useful for a gig worker whose income may arrive in several small amounts. A simple personal log can make it much easier to spot an unexpected change than trying to reconstruct everything from memory.
A realistic week with uneven income
Imagine I spend several days driving for work, with a busy weekend followed by a quiet start to the next week. My main concern is not long-term investing; it is keeping ordinary expenses from colliding with an irregular flow of earnings. In that situation, I would use Ualett as part of a short-term cash-flow routine: check what is available, decide what must remain untouched for essentials, and avoid treating accessible money as extra income.
The last point is easy to underestimate. Faster access can feel like earning more, but it does not change the total amount I make. I would set a personal limit before using any early-access or cash-flow feature, leaving room for fuel, taxes, maintenance, and slower days. That discipline is the difference between a useful bridge and a cycle of repeatedly pulling forward money needed later.
I would also compare the app’s convenience with the cost and timing of my usual alternatives before making it part of my routine. My existing bank account might be slower for a particular need but simpler for regular deposits. A budgeting app might offer better spending visibility. A payment card or employer-provided option might fit my work arrangement more directly. Ualett makes the most sense when its gig-worker focus solves a problem those alternatives leave unresolved.
Where the experience may feel limited
The same specialization that makes Ualett appealing can make it a poor fit for someone looking for a complete financial home. I would not choose it automatically for detailed household budgeting, investment management, extensive savings goals, or conventional branch-style banking. If those are my main priorities, a full-service bank or a dedicated budgeting product may be more appropriate.
I would also be cautious if my income does not follow the kind of gig-work pattern the app is designed around. A person paid through a standard employer, a freelancer with infrequent invoices, or someone managing several unrelated businesses may need a different workflow. The app may still be useful in some cases, but I would not assume that a gig-worker label guarantees compatibility with every form of independent income.
There is also a behavioral limitation: convenience can encourage impulsive decisions. If I tend to spend available funds immediately, any service centered on access to earnings requires a clear personal budget beside it. Ualett cannot decide which money is safe to use for rent, taxes, or vehicle repairs. I would keep those categories in a separate plan, even if the app makes day-to-day access easier.
Questions I would answer before signing up
The first question is whether the app is genuinely free for the actions I intend to use. The download price is free, but that alone does not answer every possible cost question in a financial service. Before relying on it, I would read the current terms and fee disclosures for the exact feature I plan to use, paying attention to timing, eligibility, and any conditions shown during the process.
The second question is whether my phone can run it. Android users need version 8.0 or later, so I would check that before troubleshooting an installation problem. I would also update the operating system where possible, because financial apps should be used on a device that still receives meaningful security support.
The third is what happens if I change my mind. I would look for account-management and support instructions before committing money-related activity to the service. Knowing how to update contact details, review access, request help, or close an account is part of responsible use, not an afterthought.
The fourth is whether the app fits my actual timing needs. I would not assume that a request made in the app means funds will always be available at the exact moment I want. I would read the on-screen explanation for each transaction and keep a backup plan for essential bills, especially during weekends, holidays, or unusually slow work periods.
Finally, I would ask whether I am comfortable with the information-sharing choices presented during setup and use. I would read privacy explanations, review permissions, and avoid connecting anything I do not need. That approach gives me more control than accepting every prompt simply to reach the home screen faster.
Who should use it—and who should skip it
I would recommend trying Ualett if you are a gig worker who regularly deals with uneven cash flow and wants a finance app aimed at that working life. It is especially worth considering when your current bank handles ordinary deposits well but does not address the timing problem that comes with independent work. The app’s long availability, broad install base, and strong average rating make it reasonable to investigate rather than dismiss.
I would skip it if I want one app to handle every part of my financial life, or if my income is already stable and the specialized purpose adds complexity without solving a real problem. I would also avoid depending on it as my only emergency plan. Keeping a conventional bank relationship or another reliable way to pay essential expenses is sensible, particularly when income is unpredictable.
My cautious verdict
My view of Ualett is positive but deliberately practical. Its best quality is not that it tries to be everything; it is that it speaks directly to the cash-flow pressure experienced by gig workers. The free app, Everyone rating, Android 8.0 compatibility, and established presence make it accessible to many people, while the 2.73.0 release shows that the product remains actively presented as a current option.
Still, I would judge it through control rather than convenience alone. Read every financial prompt, inspect permissions, protect the account, keep personal records, and compare the exact workflow with your bank or other alternatives. If Ualett helps you manage timing without encouraging you to spend tomorrow’s earnings today, it can be a useful addition. If you need broad banking, detailed planning, or a service for a completely different income pattern, another option may serve you better.
My recommendation is to treat Ualett as a focused tool, not a financial safety net. Used with a separate budget and a backup payment plan, it may fit the daily reality of gig work well. Used without those safeguards, its convenience could hide the very cash-flow pressure it is meant to ease.
Pros
- Fast access to earned wages between regular paydays.
- Simple mobile application with a straightforward cash-out process.
- Can help cover unexpected expenses without using a credit card.
- Useful for workers with irregular income or changing schedules.
- Transparent repayment timing can make advances easier to plan.
Cons
- Eligibility may depend on employer participation and payroll data.
- Advance limits may be too low for larger emergency expenses.
- Fees or optional tips can increase the total cost of using advances.
- Frequent advances may make future paychecks harder to manage.
- Availability and features may vary by location and employment status.
FAQs for Ualett
What is Ualett and what can I use it for?
Ualett is a mobile financial application designed to help users manage everyday money-related activities from their phone. Depending on your location and eligibility, it may provide services such as account management, payments, transfers, or access to other financial features. After reviewing the app, I found that the available tools can vary by country, so you should check the official description and local terms before registering.
Is Ualett available for everyone, and what do I need to sign up?
Ualett may not be available to every user or in every region. Registration generally requires a compatible Android or iOS device, a valid phone number or email address, and personal information needed for identity verification. Some features may also depend on age, residency, or financial eligibility. Before downloading, make sure your country is supported and that you can provide accurate documentation if requested.
Is Ualett safe to use for personal financial information?
Ualett handles sensitive personal and potentially financial information, so security should be an important consideration before creating an account. The app may use login protection, verification steps, and encrypted connections, but users should still install it only from an official app store. Avoid sharing passwords or verification codes, enable available security options, and review the privacy policy to understand how your data is collected and used.
Does Ualett charge fees for its services?
The cost of using Ualett depends on the specific service, transaction type, and your location. Some functions may be free, while transfers, withdrawals, card-related operations, currency conversion, or other financial services could involve fees. I recommend checking the fee schedule inside the app and reviewing the final confirmation screen before approving a transaction, since charges and limits can change over time.
What should I do if a Ualett transaction fails or my account is restricted?
If a transaction does not go through, first check your internet connection, account balance, transaction limits, recipient details, and whether your identity verification is complete. Avoid repeatedly submitting the same payment until you understand the error, as this could create duplicate attempts. For account restrictions or unresolved issues, use Ualett’s official support channels and keep screenshots, reference numbers, and transaction details available for faster assistance.

Ualett
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@ualett.com, visit https://www.ualett.com, or review their https://ualett.com/privacy-policy/.










